Direct answer: capacity planning for an accounting practice means matching the work coming in with the real hours your team has available, then controlling how that work moves through the firm. If your team looks busy but deadlines still feel fragile, the issue is usually not effort. It is workflow design, work in progress, review capacity, or unclear ownership.
This guide is for UK practice owners, operations leads and office managers who need a practical way to run recurring compliance work without relying on memory, heroics or constant chasing. It combines Rachel Harris's workflow thinking with a simple capacity model you can actually use: demand, available hours, bottlenecks, WIP and a weekly review.
"Don't just start."
That line from Rachel captures the whole point. Good accounting workflow management is not about keeping everyone occupied. It is about making sure the right work is ready, assigned, reviewed and delivered on time.
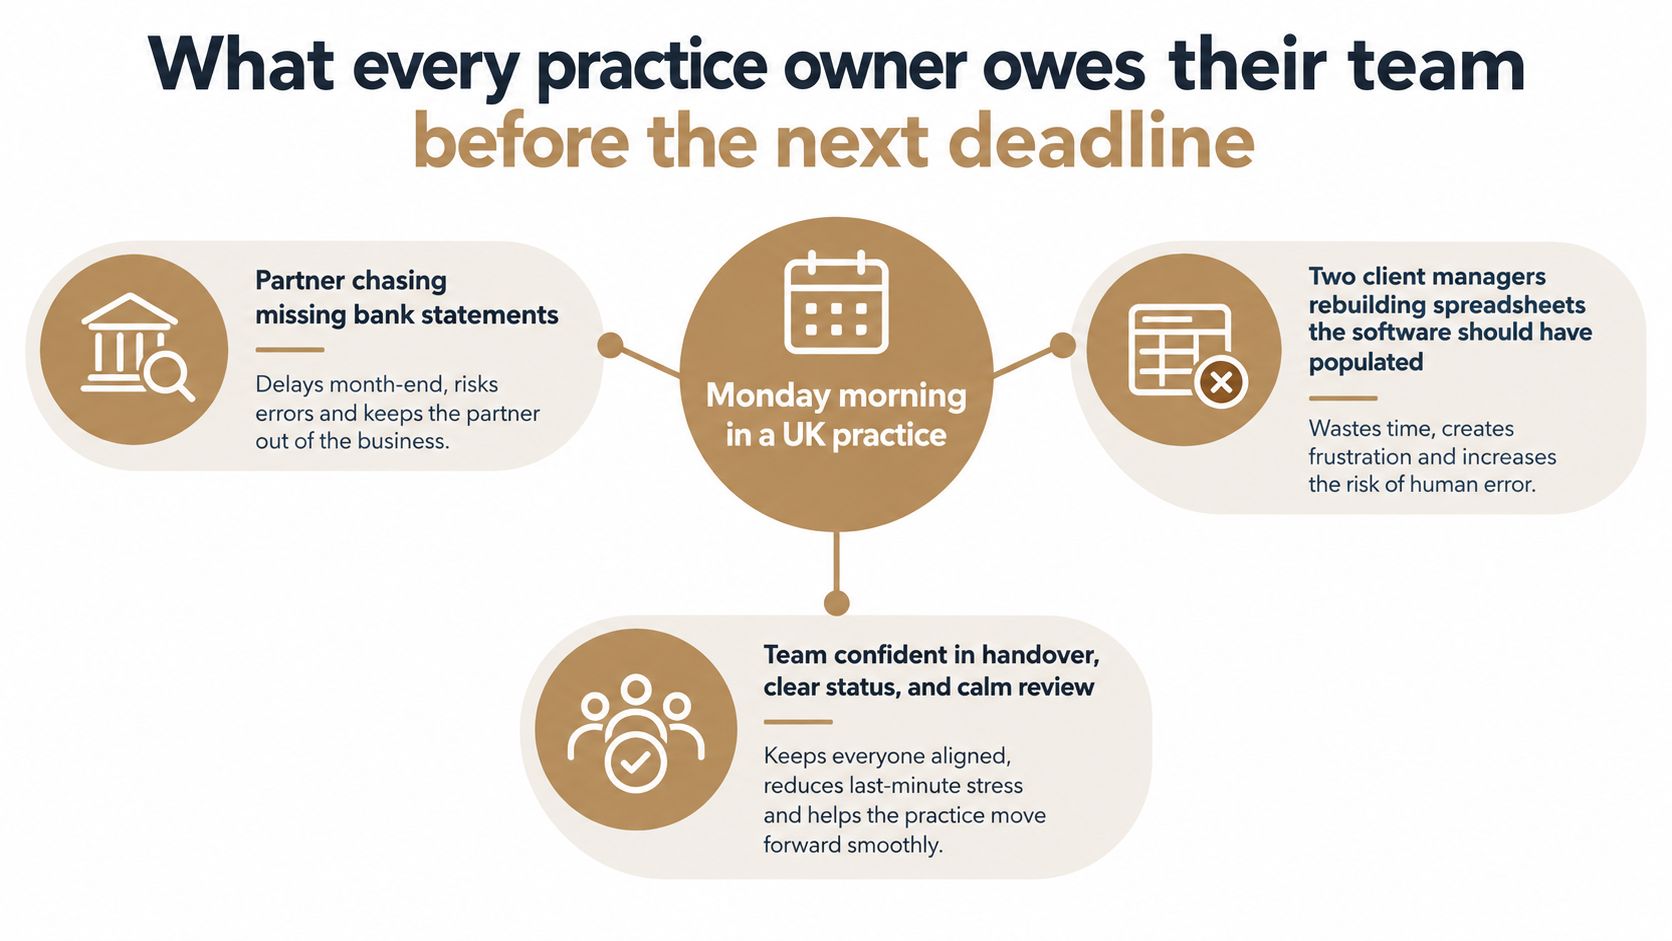
Table of Contents
- What accounting workflow management means in practice
- Why capacity planning breaks in accounting firms
- The five-part capacity model for an accounting practice
- How to build an accounting workflow template that your team will use
- A simple capacity planning template for accountants
- How workflow software for accountants should support the process
- MTD and recurring deadline pressure in UK practices
- A worked example, from records request to booked-in work
- Next step, use the template and review one live workflow this week
- Full episode transcript
What accounting workflow management means in practice
Accounting workflow management is the design and control of how work moves from client request to final completion. That includes:
-
the steps in the job
-
who owns each stage
-
what information must be present before work starts
-
where review happens
-
what counts as complete
-
what happens when something is missing or late
A long task list is not a workflow. A workflow is the repeatable route the work takes through the practice.
Rachel and James describe one of the most common failures clearly: a junior starts a job, gets halfway through, finds key information missing, writes a list of queries, sends it back up the chain, and the file stalls. The team is active, but the job is not flowing.
"Don't just start."
That is why workflow management starts before preparation. It starts with the records request, the booking-in check, and a decision on whether the file is genuinely ready.
A practical workflow for an accounting practice usually needs five visible components:
| Component | Purpose | Typical owner |
|---|---|---|
| Process map | Shows stages, handoffs and decision points | Operations lead |
| Role ownership | Makes responsibility visible | Practice manager |
| Controls | Defines readiness, review and approval rules | Reviewer or manager |
| Capacity plan | Shows whether the team can actually deliver | Practice owner or operations lead |
| KPI view | Tracks delays, WIP, bottlenecks and rework | Practice owner |
If you are tightening one process first, client onboarding or records collection is usually the best place to begin. It exposes handoffs, missing information, unclear deadlines and weak ownership very quickly.
Why capacity planning breaks in accounting firm
Capacity planning usually fails for boring reasons, not complicated ones.
The common problems are:
work is started before the records are complete
the firm counts total staff hours, not usable delivery hours
reviewer time is ignored
jobs are planned around statutory deadlines instead of internal deadlines
too many files sit half-finished in WIP
nobody owns the decision when a file is blocked
Rachel’s example of the old spreadsheet planner is useful here because it shows the principle in simple terms. Before software, the team blocked out leave, study and non-working days first. Then they left room for WIP and admin. Only after that did they allocate client work.
“One of those days would just be finalizing jobs, admin, bits and bobs.”
That is more realistic than pretending five full days are available for chargeable work every week.
Another recurring issue is false urgency. Clients send records in and expect instant turnaround. But if the practice has a visible planner, the team can say when the work is actually booked for. That protects both expectations and capacity.
“Just to let you know, this is booked in for four weeks time.”
The five-part capacity model for an accounting practice
A useful capacity model for a UK firm has five parts: demand, available hours, bottlenecks, work in progress and a weekly review. If one of those parts is missing, the practice tends to run on stress instead of control.
1. Measure demand
Demand is all the work the practice is expected to deliver. That includes more than year-end accounts or tax returns.
Count:
recurring compliance work
payroll, VAT and bookkeeping cycles
annual accounts and corporation tax
self assessment work
onboarding and cleanup work
advisory projects already sold
known reactive work that reliably appears
For demand to be useful, it must be visible by due date and by stage, not just as a total number of jobs.
A practical demand list should show:
client name
service type
deadline
readiness status
estimated effort
reviewer needed
owner
If your firm uses an accounting workflow template, those fields should be standard for every recurring service line.
2. Calculate realistic available hours
Available hours are not the same as contracted hours.
Start with total working time, then remove:
annual leave
bank holidays
training
internal meetings
admin time
management time
sickness allowance if you use one
a buffer for WIP and mop-up work
Rachel and James talked about blocking out leave and then reserving one WIP day each week. That is a useful discipline even if your firm does not literally hold Friday as a WIP day.
Here is a simple planning example:
5 people x 37.5 hours = 187.5 weekly hours
less leave and holidays averaged weekly = 12 hours
less meetings and admin = 20 hours
less training and management time = 10 hours
less WIP/review buffer = 18 hours
realistic available hours = 127.5 hours
The point is not the exact number. The point is that usable capacity is always lower than headline hours.
3. Identify bottlenecks
A bottleneck is the stage where work piles up faster than it leaves.
In accountancy practices, common bottlenecks are:
records checking before work starts
bookkeeping review
final accounts review
partner approval
client query resolution
waiting for missing documents
A rising queue of files waiting for review does not mean production staff are slow. It may mean reviewer time has not been protected.
Rachel’s description of stop-start work is the warning sign. Half-done files feel like progress, but they create hidden queueing and repeat handling.
“You’re stopping and starting, stopping and starting.”
If the same stage blocks files every week, that stage is the constraint your capacity plan must address first.
4. Control work in progress
WIP is work started but not completed. Too much WIP makes a firm feel busy while reducing actual throughput.
Good WIP control means:
fewer jobs started at once
clear entry criteria before work begins
named ownership for blocked files
an exception queue for incomplete records
visible review status
This is where Rachel’s booking-in process matters. The file should be checked against last year’s information, the records request, and where possible the balance sheet, before preparation starts.
That does not mean every query must be resolved first. It means the person allocating the work makes a deliberate decision that there is enough to start.
5. Run a weekly capacity review
The weekly review is the heartbeat of accounting workflow management.
It should answer five questions:
What work must move this week?
Which jobs are blocked?
What is waiting for review?
Who is over capacity?
What needs to change before next week?
This review does not need expensive software. Rachel and James explicitly make the point that you do not need a complicated tech stack to do this well. A spreadsheet can work if the process and ownership are clear.
The key is consistency. Review the same measures each week:
live files due in the next 2 to 6 weeks
available hours by person or team
WIP count
files waiting for client information
files waiting for review
overdue jobs
exceptions needing a decision
How to build an accounting workflow template that your team will use
A good accounting workflow template should make work easier to start, easier to hand over and easier to review.
For each recurring workflow, document:
Trigger: what starts the workflow?
Readiness check: what must be present before the work begins?
Preparation stage: who does the first-pass work?
Review stage: who checks it and against what standard?
Approval stage: who signs off or submits?
Exception route: what happens if information is late or incomplete?
Completion evidence: what proves the job is done?
For example, an annual accounts workflow template might include:
| Stage | Owner | Entry rule | Output |
|---|---|---|---|
| Records request | Client manager | Year end reached | Request sent |
| Booking in | Client manager or senior | Core records received | Ready / not ready decision |
| Prep | Junior or semi-senior | File ready to start | Draft accounts and queries |
| Review | Manager | Draft complete, support attached | Review notes or approval |
| Final approval | Partner or authorised reviewer | Review cleared | Accounts approved and sent |
| Completion | Admin or manager | Filing/submission complete | Evidence saved |
If the template does not define what happens when the file is not ready, the team will improvise. That is where weak workflow creeps back in.
A simple capacity planning template for accountants
If you want a capacity planning template that is simple enough to use weekly, build it with two views.
View 1: team capacity
Include columns for:
-
team member
-
contracted weekly hours
-
leave booked
-
fixed meetings/admin
-
review responsibility
-
WIP allowance
-
realistic available hours
View 2: work demand
Include columns for:
-
client
-
service
-
due date
-
current stage
-
estimated prep hours
-
estimated review hours
-
owner
-
blocked yes/no
-
notes
What the template should tell you at a glance
By the end of the weekly review, you should be able to see:
-
whether demand exceeds capacity
-
where work is piling up
-
which files should not be started yet
-
which reviewer is the constraint
-
which client deadlines need expectation management
If you want help turning this into a repeatable operating model, Accountant She's Systems In Practice and How to Implement Systems & Processes toolkit are the most relevant next steps.
How workflow software for accountants should support the process
Workflow software for accountants can be useful, but only after the process is clear.
Use software to support:
-
recurring job creation
-
standard statuses
-
deadline visibility
-
ownership
-
notifications
-
audit trail
-
KPI reporting
How to Implement Processes and Procedures toolkit
Do not expect software to solve:
-
poor records requests
-
unclear entry criteria
-
no review capacity
-
weak ownership
-
undefined exception handling
Rachel's point is practical. The planner works because the work has already been thought through. Software can make that easier to run, but it cannot design the operating model for you.
MTD and recurring deadline pressure in UK practices
Making Tax Digital increases the need for a repeatable workflow and a visible capacity plan.
As of 14 October 2026, HMRC states that MTD for Income Tax became mandatory from 6 April 2026 for sole traders and landlords with qualifying income over £50,000 in the 2024-25 tax year. Affected taxpayers must keep digital records, use compatible software and send quarterly updates for each business. HMRC also makes clear that quarterly updates are summaries of income and expense totals, not final tax returns (HMRC collection, before you use this guide, quarterly updates).
For standard quarterly periods, the 2026-27 deadlines are:
| Quarter | Period end | Deadline |
|---|---|---|
| Q1 | 5 July 2026 | 7 August 2026 |
| Q2 | 5 October 2026 | 7 November 2026 |
| Q3 | 5 January 2027 | 7 February 2027 |
| Q4 | 5 April 2027 | 7 May 2027 |
HMRC also says it will not apply penalty points for late quarterly updates during the 2026-27 tax year, although other filing and payment penalties can still apply (HMRC update guidance, HMRC news release).
Operationally, that means firms need to plan for more recurring touchpoints, more review moments and clearer client cut-off rules. If your practice leaves work to the statutory deadline, MTD will expose that weakness faster.
This guide is educational. For client-specific tax positions, filing obligations or software choices, use current HMRC guidance and take tailored professional advice where needed.
A worked example, from records request to booked-in work
Rachel and James give a very practical example of what good flow looks like.
Step 1: request the right records the first time
Instead of sending a generic annual email, use last year's completed file to list everything needed to do the job this year. That reduces back-and-forth and shortens the time from receipt to preparation.
They also describe adding practical help into the request itself, such as links to videos showing clients how to download bank statements.
"If you can get all the information you need with one records request, yeah, that whole process is going to be a lot quicker."
Step 2: check the file before allocating work
When the records arrive, someone checks whether they are complete enough to start. In their model, this is often the person who owns the client relationship, or a manager who can judge whether the file is genuinely ready.
That check may include:
-
comparing against last year's records list
-
comparing against the records request sent
-
checking for evidence for each balance sheet line where relevant
-
deciding whether there is enough to start without creating avoidable rework
Step 3: book the work into the planner
Only after the readiness check does the work go into the planner.
For year-end work, the planner can allocate blocks of time by client and by person. For monthly or quarterly services, the planner may block standard windows for payroll, bookkeeping, VAT and management accounts.
Rachel also makes an important point about internal deadlines. The team brings work forward so that statutory deadlines do not become operational deadlines. For example, VAT work is planned to be completed before the filing week wherever possible.
Step 4: protect WIP and mop-up time
The planner should not assume every hour is available for fresh production work. A WIP allowance protects time for finishing files, clearing review points, handling admin and absorbing normal practice friction.
Step 5: use the planner to set client expectations
A visible planner also improves communication. When records come in, the team can tell the client when the work is booked. That reduces unstructured chasing and protects the practice from the expectation that everything should be turned around immediately.
Next step, use the template and review one live workflow this week
If your current system lives in people's heads, start small.
This week:
-
Pick one recurring workflow.
-
Write the entry criteria before work starts.
-
Calculate realistic available hours for the next two weeks.
-
Count your current WIP.
-
Hold one weekly review and identify one bottleneck.
That is enough to expose where capacity is really being lost.
If you want structure and implementation support, start with Systems In Practice or the How to Implement Systems & Processes toolkit.
In short, better capacity planning is rarely about squeezing more effort from the team. It is about controlling when work starts, protecting review time, limiting WIP and making the weekly decision points visible.
Accountant She Ltd provides educational resources, templates and training for accountants and practice owners who want clearer systems and stronger implementation.
Full episode transcript
Rachel Harris: Welcome to the Accountant She Practice Owners Podcast with me, your host, Rachel Harris. This podcast exists to help you unlock my secrets to running, starting and scaling a seven-figure accounting firm. Join me as I share insider knowledge and proven strategies to elevate your accounting firm.
Welcome back to the Practice Owners Podcast. This is week two of your four-week guide to the tax return bootcamp for accountants. Today we're talking about workflow management and capacity management, which is a great topic all year round, but very timely when we're talking about January. We are going to open the books and show you exactly how we manage workflow start to finish.
In preparation for this episode, I ran a report looking at what happened during busy season last year. Our happiness and overall employee net promoter score did not change from November all the way through to March. Post-March, it went up. Today we're going to talk to you about how you manage workflow without making your team really stressed and without making you really stressed as well.
Rachel Harris: Can you talk us through, outside of January, the process from receiving records from a client all the way through to planning that workflow for a team member or even yourself? Because you can use capacity planning as a one-man band and you can use capacity planning with a much larger team.
James: Records requests are underrated. I don't think people realise how much time they can save. Automated or not automated, if you get it right and you get all the information to the client first time around, life is good.
The one thing I hated the most as a junior was when my manager gave me a job to start and I could only do half of it. I'd do half the job, then write a list of all the things I needed. It then goes back to the manager, the manager has to check it, the manager sends it on, no billing comes back to me. If you have to do that for all of your jobs, you're stopping and starting, stopping and starting. If you can get all the information you need with one records request, that whole process is going to be a lot quicker.
Rachel Harris: We've made a lot of process improvements to records requests. On our working papers, we have a planning section and whenever we request the records we either send the automated request or, if our CRM cannot do that, a personalised request. If we can, we look at last year's records to see everything we'd need, copy that and send it out. That saves going backwards and forwards.
When we finish a job, we make a list of every single piece of information that we needed to finish the job, which we can then pick up at the beginning of next year and request again.
Even little things like requesting bank statements, we have a list of the most popular banks in the UK with hyperlinks to video tutorials showing clients how to download bank statements. We are getting records requests right, embedding videos to explain frequently asked questions, and over-explaining why we need those records.
This is the standard request that we send. Based on the work that we did together last year, we'll also need this. If you can give it to all of me up front, that would be great.
Rachel Harris: When the records come in, we check them to make sure it's everything. Don't just start.
When the client replies with, "I've done all my homework, please find attached", you know what it's like when there's just a zip file or five attachments and you think it's all there. Then it's only when you get halfway through the job that you realise there is no loan bank statement.
Rachel Harris: Talk to me about how a very junior member of staff would book those records in.
James: Depending on who is responsible for the job, it might be one of our junior managers in client relations, or it might be the manager who looks after the portfolio and has juniors working for them. But whoever has the client relationship would generally request the information and check it before passing it over to the person that's going to do the job.
They would check it to last year. They would run a balance sheet if they've got access to the accounting software and have a quick flip through to make sure they've got evidence for every balance sheet item on there. At the very least, you can probably get draft accounts out with that, and you'll know there are initial queries but enough records to start the job.
That's why it's often easier if a manager or you are checking the records, because a junior might not know when they can or can't start a job.
Rachel Harris: So we request the records, the records come in, someone reviews the records to last year and then we start the job.
James: If it's a new client, it is more of a common sense check. You check it against the email that you've sent, bank statements, fixed assets and all of those things. Then run a balance sheet, check there's nothing odd on there, and then start on the work.
Rachel Harris: The work is then allocated to our planner. We have different planners for different teams. A lot of people think that they need really expensive software. James has had a lot of love on his spreadsheet, which is workflow and capacity management, so we're going to talk you through how we use that spreadsheet.
James: We used to have an Excel spreadsheet that was a bit like a Gantt chart. The manager would look after the spreadsheet and you'd have the team members on the left, probably for one month or five or six weeks at a time, with dates across the top.
First thing that we do is block out leave, holiday and study. Block out the days where you're not in. Then one day of every week we would have as a WIP day.
Rachel Harris: People might not know what WIP is.
James: A day a week blocked out for work in progress. That would be a day where we wouldn't have a new job on the planner. We worked out that over a five-day work week, one of those days would be finalising jobs, admin and bits and bobs. It was a mop-up day.
It would never actually happen on that day. If Friday was blocked out as WIP, you would do 80% of a day every day as billable, but 20% isn't. It was blocked out that way to help you understand that you've got capacity to do mopping up, clear your inbox, admin and sort your life out.
We'd have little squares or rectangles with the client's name on, and they would be put on for half a day, a day, or a day and a half depending on how big the job is. That would be put on the planner for when we were able to start it.
Because we had all the records in on this planner, when a client sent us their records we could say, "Just to let you know, this is booked in for four weeks time." That was really good for expectations because it stopped clients chasing us after a week or two. They didn't realise that we had weeks worth of work lined up.
It would also help us identify jobs that were taking too long or staff that were working too slowly. What would happen is they wouldn't do it in the allotted time, so you'd have to move these jobs along and then you'd end up with blank spaces. Staff with lots of blank spaces were either where the job had taken too long or they were struggling.
When the staff see it as well, it's a really good motivator because they know what they are going to do that month. They don't have to ask what the next job is because it's put on there.
Rachel Harris: That works for year-end services like accounts, corporation tax and self assessment. But some of the smaller jobs that take less than half an hour, like payroll, work slightly differently.
We have two different teams in our business. We have a year-end team and we have business services. Business services is monthly and quarterly services. Each month, they have days blocked out. It might be three or four days in the month blocked out for payroll. Then they'll have days blocked out for bookkeeping.
We've built what we think of as the perfect business services month. It has VAT returns being done at exactly the right time, proactively and not on the seventh. It has payroll being done at exactly the right time, with the directors only at the beginning of the month and the variables at the end. CIS is in the right place, management accounts are in the right place. It is the perfect business services month, which we run on repeat.
James: That team is based on internal deadlines. Whatever the client deadlines are, that's almost ignored. We have internal deadlines that are brought forward. So for our team, the VAT deadline is the end of the month. We try to avoid filing or doing any VAT work between the first and the seventh, unless it's for the following month.
Our business services team should be able to take that first week of the month off on annual leave and not see any drama or difference because the work is done in advance.
Rachel Harris: With workflow and capacity management, a lot of people think they need really expensive software that talks to their CRM and plans it all. We literally automate records requests. The trigger point to it going on the work planner is the records coming in.