If you use your own vehicle for work, HMRC mileage rates can let you claim or be reimbursed for qualifying business travel. For 2025-26, the approved rate for cars and vans is 45p per business mile for the first 10,000 miles and 25p per mile after that. From 6 April 2026, the first 10,000 miles rate rises to 55p, while the rate above 10,000 miles stays at 25p, according to HMRC’s published update on approved mileage allowance payments and the GOV.UK employer rates pages for 2025-26 and 2026-27.
This guide is for sole traders, directors and employees who want to understand what they can claim, which journeys count, how electric vehicles fit in, and how to avoid the common double-claim mistakes.
As Rachel Harris puts it, “This is the tax tip that is genuinely free money, and I see business owners leave it on the table every single day.”
Who owns the vehicle?
Was the journey genuinely for business?
Which HMRC system applies?
That tells you whether you are dealing with approved mileage rates, self-employed simplified expenses, or separate company car fuel rules.
Table of Contents
- What the current HMRC mileage rates are
- How mileage allowance works for employees
- Claiming mileage if you are self-employed
- Company cars and business mileage allowance rules
- Electric car mileage allowance and charging evidence
- Motorcycle, bicycle and passenger rates
- What to put in your mileage log
- Common mileage claim mistakes to avoid
- Key lesson takeaways
- Conclusion and next step
What the current HMRC mileage rates are
For employees using their own vehicle for qualifying business travel, HMRC’s Approved Mileage Allowance Payments, usually shortened to AMAPs, are the main benchmark.
Current position, checked against GOV.UK:
| Vehicle type | HMRC rate |
|---|---|
| Cars and vans, first 10,000 business miles in 2025-26 | 45p per mile |
| Cars and vans, over 10,000 business miles in 2025-26 | 25p per mile |
| Cars and vans, first 10,000 business miles from 6 April 2026 | 55p per mile |
| Cars and vans, over 10,000 business miles from 6 April 2026 | 25p per mile |
| Motorcycles | 24p per mile |
| Bicycles | 20p per mile |
| Additional passenger rate, fellow employee in a car or van | 5p per passenger per mile |
You can check the current approved rates on HMRC's travel mileage and fuel rates page, the GOV.UK employer rates page for 2026-27, and the related HMRC Employment Income Manual guidance.
These rates matter in different ways depending on who is claiming:
-
Employees use them as the tax-free benchmark for employer mileage payments.
-
Sole traders may use the mileage basis under simplified expenses to calculate a deduction.
-
Directors need to check whether the car is personally owned or is a company car.
-
Company car drivers follow separate advisory fuel rate rules for the fuel element.
As Rachel says in the lesson, "The basic idea for mileage is lovely and simple. For every business mile you drive in your own car, your business can pay you a set amount per mile."
Which journeys count as business mileage
Not every mile you drive for work is claimable.
In general, travel between home and a permanent workplace is ordinary commuting, so it does not count as business mileage. Qualifying business mileage is more likely to include journeys to:
-
a client meeting;
-
a temporary workplace;
-
a site visit;
-
a training venue that qualifies under the rules;
-
another business location visited in the course of your work.
That is why your mileage record needs more than a total number. You need enough detail to show where you went and why the journey was for business.
How mileage allowance works for employees
For employees, mileage allowance is not an automatic cash right. It is the approved tax benchmark an employer can usually reimburse for business miles in the employee's own vehicle without creating a taxable benefit.
There are three common outcomes:
| What the employer pays | Practical result |
|---|---|
| At or below the approved amount | Usually non-taxable if the journey qualifies |
| Less than the approved amount | The employee may be able to claim Mileage Allowance Relief on the shortfall |
| More than the approved amount | The excess may need to be treated as taxable earnings through payroll |
HMRC explains the framework in its travel mileage and fuel allowances guidance and EIM31330.
Worked example for an employee
Suppose an employee drives 12,000 qualifying business miles in 2025-26 using their own car.
The approved amount is:
10,000 miles x 45p = £4,500
2,000 miles x 25p = £500
Total approved amount = £5,000
If the employer pays 30p per mile for all 12,000 miles, the employee receives:
- 12,000 x 30p = £3,600
The shortfall against the approved amount is:
- £5,000 – £3,600 = £1,400
That £1,400 is not an extra amount the employer must pay. It is the possible basis for a tax relief claim by the employee, subject to the rules.
From 2026-27, the income tax treatment of the first 10,000 miles reflects the new 55p rate. National Insurance treatment needs careful payroll handling because HMRC has published a separate NIC position. GOV.UK states that for NIC purposes in 2026-27, 55p applies to all business miles. If you run payroll, this is one area to double-check before changing your expense settings on the basis of the 2026-27 employer guidance.
Claiming mileage if you are self-employed
If you are searching for claiming mileage self employed, the main point is this: you are not reimbursing yourself in the employee sense. Instead, you are using mileage to calculate a business tax deduction if you use the simplified expenses method.
For a sole trader, the mileage calculation is straightforward:
Business miles x HMRC mileage rate = allowable deduction
Example:
- 8,000 qualifying business miles x 45p = £3,600 deductible expense
That figure reduces taxable profit. It is not a separate payment created by HMRC.
This method can be useful if you want a simpler way to deal with vehicle costs, but the records still matter. HMRC expects you to keep enough evidence to support the miles you claim.
Rachel’s wording in the lesson gets to the point neatly: “Business miles multiplied by the rate paid back to you tax-free.” For sole traders, think of the same mechanism as a calculation method for your allowable deduction rather than an employer reimbursement.
For broader guidance on allowable sole trader costs, see Sole Trader Expenses Explained.
What the mileage rate already covers
If a sole trader uses the mileage basis for a vehicle, the rate is intended to cover the relevant running costs already built into the simplified method. That means you should not also claim separate actual costs for the same vehicle such as:
fuel;
insurance;
servicing and repairs;
maintenance;
road tax;
depreciation or capital value costs.
This is one of the most common errors in mileage claims. You use either the mileage basis or the actual cost basis for the relevant costs, not both for the same vehicle calculation.
A practical mileage record for a sole trader should include:
date;
start point;
destination;
reason for the journey;
miles travelled.
Adding the client name, site name and vehicle registration can make your records much easier to review later.
Company cars and business mileage allowance rules
Company cars follow a different set of rules from employee-owned vehicles.
If the vehicle is a company car, the usual employee mileage rates of 45p, 25p or 55p are not the starting point for the fuel element. Instead, HMRC publishes Advisory Fuel Rates, usually called AFRs, for reimbursing business fuel or calculating repayment for private fuel.
Current AFRs are published by HMRC at Advisory fuel rates. The correct rate depends on:
fuel type;
engine size;
journey date;
whether the vehicle is electric and, if so, how charging is treated.
Why own car and company car claims are different
This is where many mileage mistakes happen.
Rachel explains the principle clearly: “Broadly speaking, there are three situations, and it helps to know which one you’re in. There is your own car, where you simply claim the mileage rate. Then there is a company car, which works completely differently.”
Use this simple rule:
Own car or van used by an employee, use AMAP rules.
Company car, use the relevant advisory fuel rate for the fuel element.
Before any claim is approved, check:
Who owns or provides the vehicle?
Was the journey business travel or commuting?
Is the claim for full mileage reimbursement or only the fuel element?
Which HMRC rate applied on the date of travel?
If you are a director using a personally owned vehicle for company business, the AMAP framework may still apply because the company is reimbursing your own car use, not a company car arrangement.
For wider company expense planning, see LTD Company Expenses Explained.
Electric car mileage allowance and charging evidence
Electric car mileage allowance depends first on ownership.
If an employee or director uses their own electric car for business journeys, the normal AMAP approach can apply in the same way as for petrol or diesel cars.
If the vehicle is a company car EV, HMRC’s advisory electric rate applies instead for the relevant energy element. HMRC’s current guidance states that, from 1 September 2026, the advisory electric rates are 7p per mile for home charging and 15p per mile for public charging, as set out in HMRC’s advisory fuel rates guidance and the 2026-27 employer guidance.
This is also where Rachel flags the biggest confusion point in the lesson: “Where it gets nuanced is if the car is a company car, or the company is paying for the charging of the electric car. Because then we move into a different set of rules, and you actually can’t have it both ways and double up.”
That means EV claims need better evidence than many older mileage systems were designed to capture.
Worked EV example for a company car
Suppose a company car EV covers 6,000 business miles and the charging pattern is:
70% charged at home
30% charged on public charging networks
The reimbursement split would be:
4,200 miles x 7p = £294
1,800 miles x 15p = £270
Total = £564
This only works if the evidence supports the split. If the business cannot show a reasonable basis for how home and public charging were identified, the calculation becomes harder to defend.
A practical EV mileage log can include:
journey date;
business purpose;
miles travelled;
vehicle registration;
charging type, home or public;
supporting receipts or charging records where available;
note of any agreed estimated split and review date.
Motorcycle, bicycle and passenger rates
HMRC mileage rates do not apply only to cars.
The current approved rates also include:
24p per mile for motorcycles;
20p per mile for bicycles;
5p per passenger per mile where an employee carries a fellow employee on a qualifying business journey in a car or van.
These figures are listed on HMRC’s mileage and fuel allowances page.
Rachel also highlights the bicycle point directly in the lesson. If you cycle for business, there is “actually mileage relief for bicycles, too.”
The same record-keeping discipline still applies. Even where the calculation is smaller, you should be able to show the date, purpose and business nature of the journey.
What to put in your mileage log
A good mileage log is often the difference between a clean claim and a messy one.
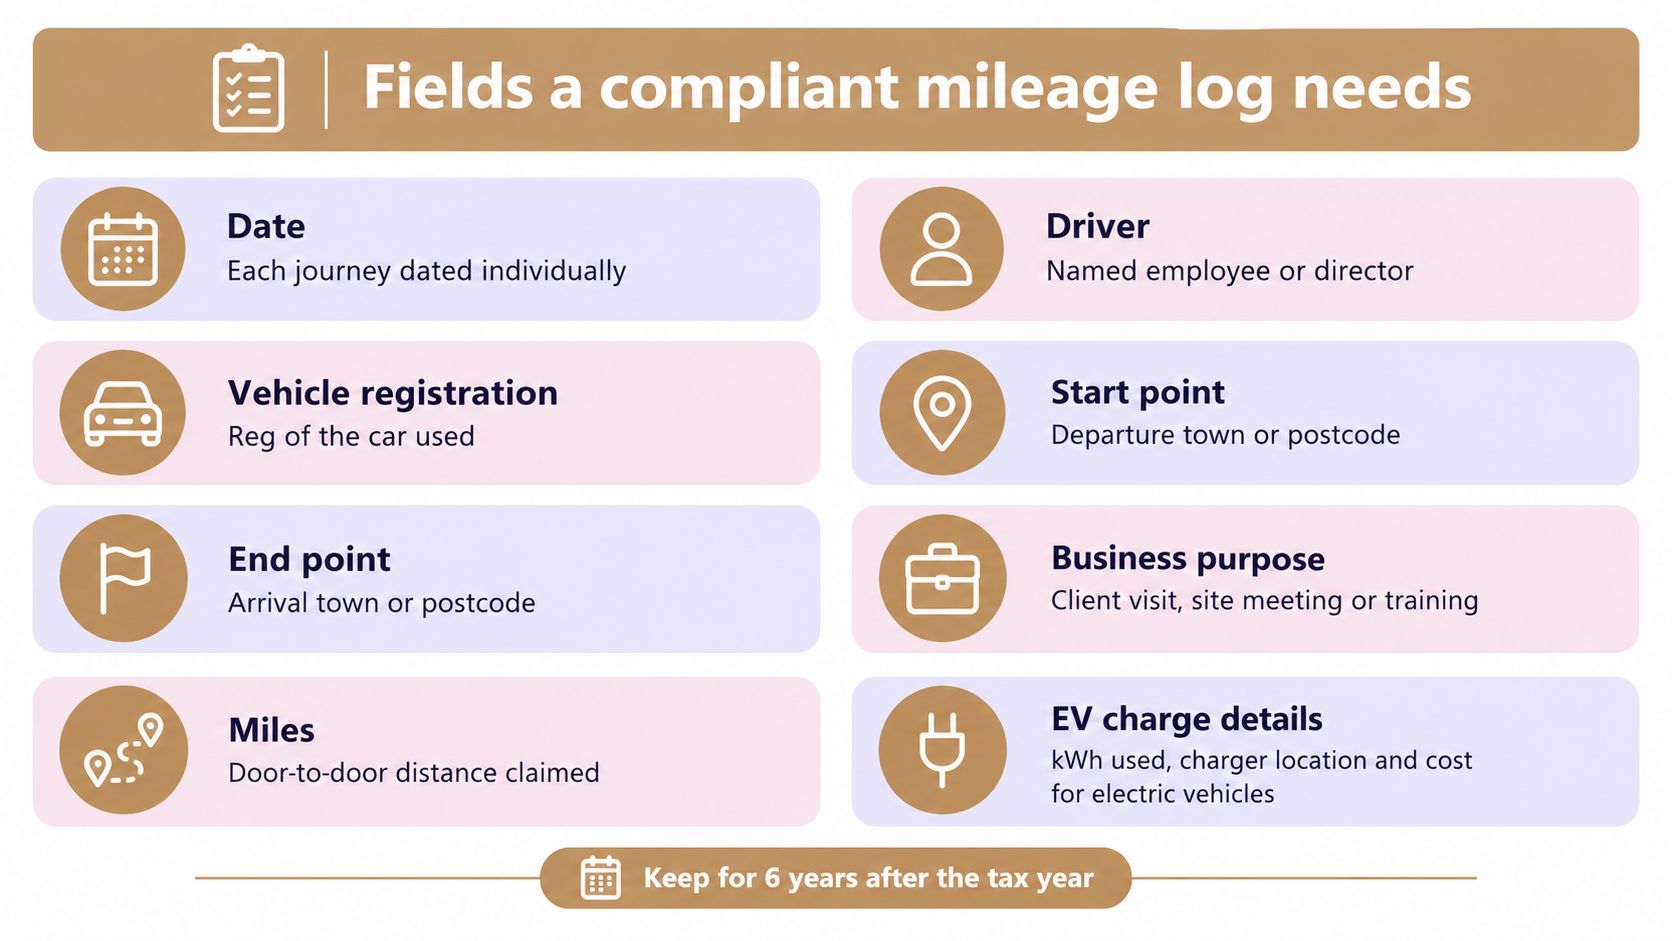
At minimum, record:
Date
Driver name
Vehicle registration
Start location
Destination
Business purpose
Business miles claimed
EV charging detail where relevant
If your journeys involve several stops, note them clearly instead of bundling everything into one unexplained total.
Rachel’s checklist in the lesson is simple and practical. She recommends “a simple spreadsheet, just noting the date, the journey, the reason, the start location, the end location, and the number of miles to claim.”
A mileage log should answer three questions quickly:
Was the journey genuinely for business?
Was the correct rate used?
Can the calculation be checked later?
Common mileage claim mistakes to avoid
These are the mistakes that cause the most confusion:
1. Claiming commuting as business mileage
Travel from home to a permanent workplace is usually ordinary commuting, not business travel.
2. Mixing up own car and company car rules
Do not pay a company car driver using the standard AMAP rates for an employee’s own vehicle.
3. Claiming mileage and actual running costs together
If you use the mileage basis for a vehicle, do not also add fuel, insurance or repairs for the same cost calculation.
4. Using a rate from the wrong period
Mileage and advisory fuel rates can change. Check the rate that applied on the date of the journey, especially around tax year or HMRC update dates.
5. Keeping weak records
An annual estimate with no journey detail is much harder to support than a proper contemporaneous mileage log.
Rachel sums up the practical fix well: set the system up once and keep it simple. In her words, “it’s one of the highest returns on the smallest amount of effort in the whole of running your business.”
Where a director’s arrangement is mixed, the business has an electric company car, or payroll has already processed claims under the wrong method, it is sensible to get tailored accounting advice before correcting the treatment.
Key lesson takeaways
Start every mileage claim by checking vehicle ownership, journey purpose and which HMRC system applies.
Employees using their own vehicle usually look first at AMAP rates.
Sole traders can use mileage rates as a deduction method, not as an employer reimbursement.
Company cars use advisory fuel rates, not the standard own-car mileage table.
Electric vehicle claims need better evidence where home and public charging are reimbursed at different rates.
A clear, complete mileage log reduces compliance risk and makes claims easier to review.
If the setup feels blurred, especially for EVs or director claims, that is the point to get tailored advice rather than guessing.
Conclusion and next step
HMRC mileage rates are straightforward once you separate the three big questions: who owns the vehicle, what sort of journey it was and whether you are dealing with reimbursement, tax relief or a business deduction.
If you want the simplest next step, review your current mileage process against the checklist in this guide and make sure your records capture enough information before the next claim is submitted.
If you want to strengthen your wider expense processes too, start with Sole Trader Expenses Explained or LTD Company Expenses Explained.
This article is based on Accountant She Vault Lesson 2, Mileage, and cross-checked against current HMRC guidance on mileage allowances and advisory fuel rates.